Ethiopia is moving to establish a new housing finance system, including a housing finance corporation and a dedicated housing fund, as the government seeks to unlock long-term mortgage financing and address the country’s deepening housing shortage.
The initiative is expected to be formalized through a new proclamation following a study led by the Ministry of Urban and Infrastructure that proposed a range of financing instruments to address Ethiopia’s longstanding residential housing crisis.
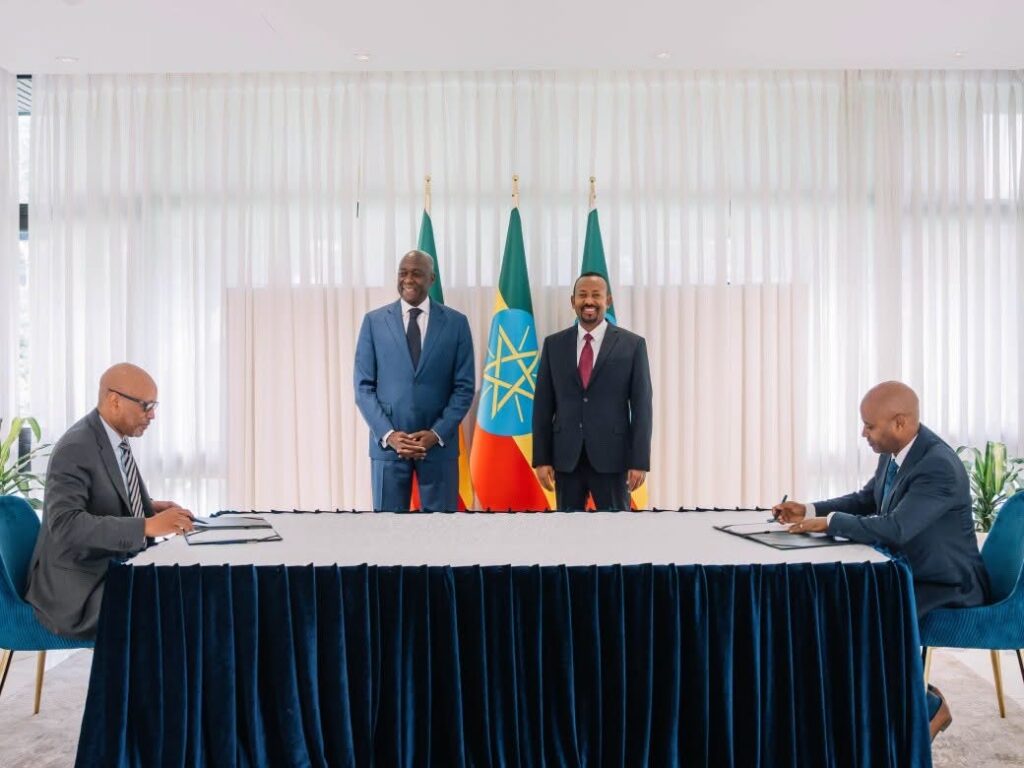
The development comes as the National Bank of Ethiopia (NBE) and the International Finance Corporation (IFC), the World Bank Group’s private-sector arm, signed a framework agreement on September 3 to support the development of a mortgage financing scheme.
Prime Minister Abiy Ahmed, who attended the signing ceremony, said the planned wholesale mortgage refinance company will be capitalized at 100 billion birr, with the IFC expected to contribute at least US$200 million.
The company is intended to address what the Prime Minister described as a long-standing liquidity mismatch in Ethiopia’s banking sector, enabling banks to provide longer-term and more accessible mortgage loans to households.
“This partnership is a critical step toward realizing our goal of delivering 1.5 million affordable, dignified homes for Ethiopian families while expanding private-sector participation in our financial system,” Abiy said in a social media post.
According to experts familiar with the proposed framework, the housing fund would mobilize resources from public and private sources and channel them into mortgage financing schemes at more affordable rates.
Under the initial proposal, employees in the public and private sectors could contribute 1.5 percent of their salaries to the fund, while the federal and regional governments could allocate 5 percent of their annual capital budgets.
The proposed fund could also mobilize resources from other domestic and international sources. In addition, the property tax regime expected to be introduced could allocate up to 10 percent of its collections to the housing fund, according to sources familiar with the proposal.
The proposal has reportedly been under development for around two years and has been discussed with relevant stakeholders.
The proposed housing finance corporation would be responsible for managing funds mobilized through the housing fund and coordinating the financing mechanism under the oversight of the National Bank of Ethiopia.
Housing demand outpaces financing
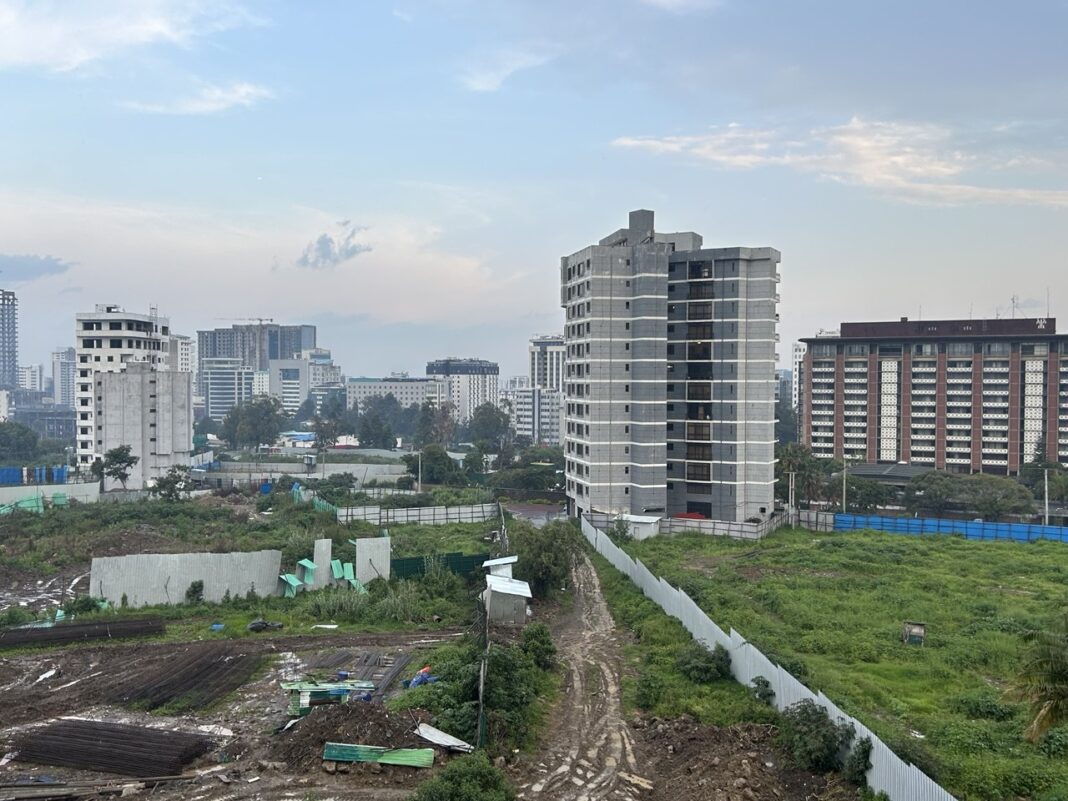
The proposed reform comes amid a severe mismatch between Ethiopia’s housing demand and the financial resources available to address it.
Various studies have highlighted the scale of the housing deficit. A 2019 assessment estimated that Ethiopia had a housing backlog of more than 1.2 million units, while more recent assessments point to the need for around 400,000 new homes annually.
A recent study by Goh Betoch Bank, a bank focused primarily on mortgage financing, estimates that additional annual housing demand in Addis Ababa alone is at least 100,000 units.
The challenge is not limited to the shortage of new homes. Of the estimated 4.4 million existing housing units in Ethiopia, around 70 percent of urban housing is reportedly below standard, creating an additional need for substantial renovation, upgrading and replacement.
Yet long-term housing finance remains severely constrained.
Experts argue that the share of bank credit reported by the NBE for the building and construction sector should not be interpreted as residential mortgage financing, as the category also includes a broad range of construction and building-related activities.
For the 2024/25 fiscal year, NBE data shows that building and construction accounted for 13.7 percent of total outstanding commercial bank loans, up from 11.1 percent in 2023/24.
However, experts say much of this financing is not structured as affordable, long-term mortgage credit. With lending rates reportedly starting at around 15 percent, housing loans remain beyond the reach of many households.
The structural problem is also linked to the maturity mismatch in Ethiopia’s banking system. Commercial banks largely mobilize short-term deposits, making it difficult for them to provide mortgages that can extend for 20 or 30 years.
Experts also point to regulatory requirements that encourage banks to maintain shorter lending maturities to limit potential losses and liquidity risks.
Goh Betoch’s earlier housing fund proposal
The idea of establishing a dedicated housing fund is not entirely new in Ethiopia.
Goh Betoch Bank, which has positioned itself as a specialized mortgage-focused bank, submitted policy recommendations to the central bank around three years ago calling for the establishment of a national housing fund.
The proposal was developed after the bank examined housing finance systems in several African countries and other international markets. It argued that a dedicated housing fund could mobilize long-term resources, including pension and provident funds, and make them available for housing finance at more suitable rates.
The bank pointed to Nigeria as one example. Under Nigeria’s National Housing Fund, contributors can access financing for the construction, purchase or renovation of residential housing. The scheme also provides relatively lower-cost housing loans and tax advantages for contributors.
Kenya provides another regional example. The country established its National Housing Development Fund in 2018 to mobilize resources for affordable housing. The fund provides long-term financing to primary mortgage lenders, including banks, microfinance institutions and savings and credit cooperatives, at relatively low and fixed rates.
Goh Betoch argued that Ethiopia could adopt a similar mechanism, with the government taking ownership of the initiative while creating an alternative source of long-term funding for mortgage lenders and housing projects.
A new chapter in Ethiopia’s mortgage banking
The proposed housing finance structure would mark a significant shift in Ethiopia’s mortgage market, which has historically lacked a dedicated institution capable of transforming long-term savings into long-term housing loans.
Goh Betoch Bank is demanding to be the first specialized mortgage-focused bank established in Ethiopia since the country’s former Housing and Savings Bank (HSB), which was formed in the mid-1970s during the Derg period through the merger of the Imperial Savings and Home Ownership Association and the Savings and Mortgage Corporation of Ethiopia.
HSB was later reconstituted as the Construction and Business Bank (CBB) in 1994. CBB eventually ceased operating as an independent bank and was merged into the state-owned Commercial Bank of Ethiopia in 2016.
Experts stated that the establishment of a wholesale mortgage refinance company would therefore introduce a new institutional layer between long-term sources of funding and commercial banks, potentially allowing banks to extend mortgage loans with significantly longer maturities.
The move also comes under Ethiopia’s evolving financial-sector framework. The 2025 banking business proclamation provides for the establishment of specialized financial institutions targeting specific areas of business, creating a legal basis for a more diversified financial system.
“If implemented as proposed, the new housing fund and mortgage refinance institution could become one of the most significant attempts yet to solve Ethiopia’s chronic housing-finance gap by bringing long-term capital into a market that has traditionally depended on short-term bank funding,” experts stated.SECO