– Regulatory and IFRS loan-loss provision differences raise questions about earnings quality
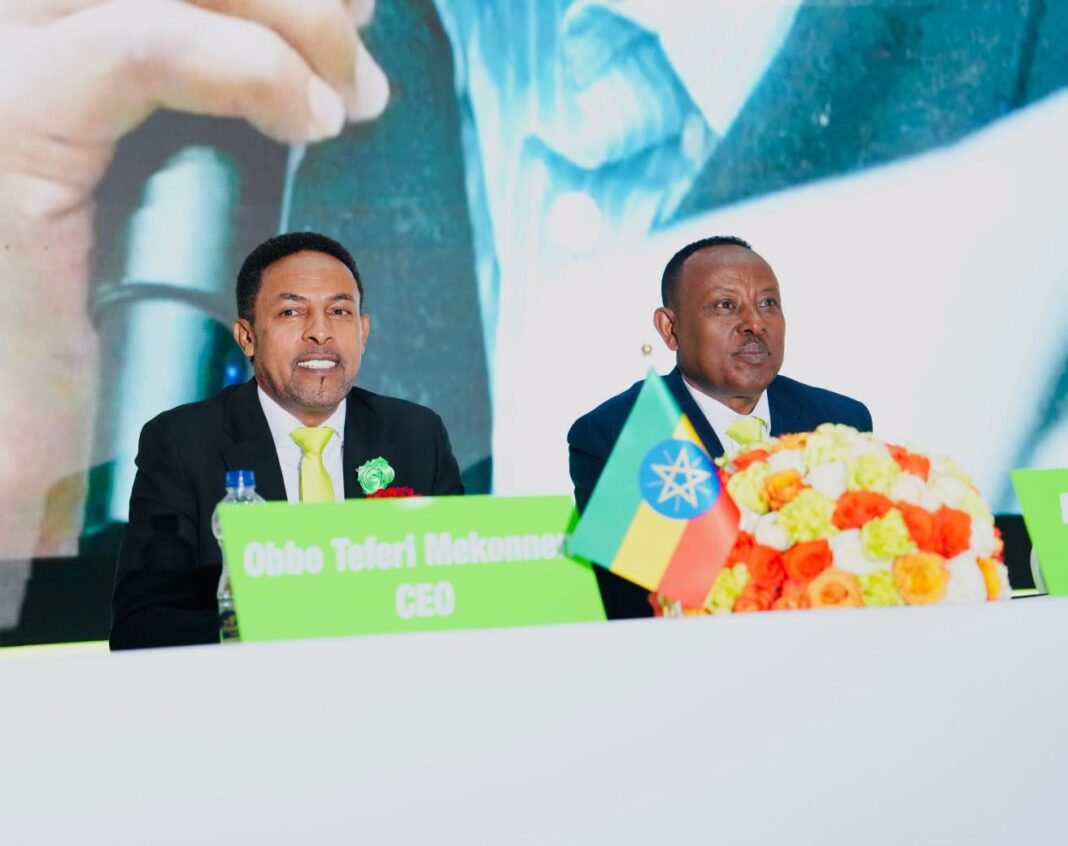
Oromia Bank, one of Ethiopia’s relatively young private lenders, reported a strong financial performance in the 2025/26 fiscal year, with profit before tax surging 49% to 3.8 billion birr, even as its foreign currency generation declined sharply in a reversal of the trend seen across much of the banking sector.
The bank’s annual report shows total assets climbed 24% to 105 billion birr, while customer deposits increased 24% to 88 billion birr. Net profit reached 2.8 billion birr, reflecting a year of significant growth in its balance sheet and earnings.
However, the bank’s foreign currency generation moved in the opposite direction, falling nearly 20% to USD 262.6 million from USD 328 million in the previous fiscal year. The USD 65.6 million decline raises questions about the bank’s ability to sustain its foreign exchange contribution at a time when access to hard currency remains a central concern for Ethiopia’s financial sector.
Export earnings fell 32% to USD 96.6 million, while inward transfers dropped sharply to USD 55.5 million. Foreign exchange dealing, by contrast, rose to USD 106.9 million and accounted for a substantial share of the bank’s reported foreign currency generation.
The divergence between strong profitability and declining foreign currency generation makes the bank’s latest results particularly notable. While the financial statements point to expanding business and stronger earnings, the foreign exchange figures suggest that growth in profitability has not translated into an increase in this important source of foreign currency.
The report also identifies differences between regulatory loan-loss provisions required by the National Bank of Ethiopia and provisions calculated under International Financial Reporting Standards, particularly IFRS 9. These differences warrant closer examination when assessing the quality and sustainability of the bank’s reported earnings.
According to the report, the bank transferred 11.6 million birr to a regulatory risk reserve because prudential provisions under the central bank’s requirements exceeded the amount recognised under IFRS 9. The report also records a 147 million birr adjustment relating to prior-year provisioning.
Such differences do not, by themselves, indicate wrongdoing or an accounting breach. Banks may calculate expected credit losses differently under regulatory rules and IFRS accounting standards. However, understanding the reasons for the adjustments, how they affect reported profit and whether they reflect changes in credit-risk assessments is important in evaluating the underlying quality of earnings.
On asset quality, Oromia Bank reported a non-performing loan ratio of 2.43%, below the 5% ceiling cited in its report. Its loans and advances, including interest-free financing, increased to 56.22 billion birr from 44.08 billion birr a year earlier. The combination of rapid lending growth and a relatively low reported NPL ratio will make the performance of its loan portfolio an important indicator to monitor in coming periods.
The bank’s total income rose 23% to 15 billion birr, while total expenses increased 17% to 11.4 billion birr, helping drive the sharper rise in pre-tax profit. Interest income from loans increased to 10.05 billion birr, but fee and commission income declined 19% to 2.4 billion birr. Income from interest-free banking and investment products rose 61% to 842.7 million birr, while other local income increased to 1.9 billion birr from 605 million birr.
The shift in income sources raises further questions about the durability of earnings growth, particularly as fee income declines and other local income rises significantly. Further detail on the composition and recurring nature of these income streams would help investors and depositors assess whether the bank’s recent profitability can be sustained.
The independent auditor issued an unmodified opinion, stating that the financial statements presented fairly, in all material respects, the bank’s financial position and performance under IFRS. The opinion provides assurance on the financial statements within the scope of the audit, but does not eliminate the need to examine changes in foreign currency generation, provisioning adjustments and the composition of income.SECO