Central bank retains interest-rate corridor despite accelerating money supply, while signalling further liquidity management measures
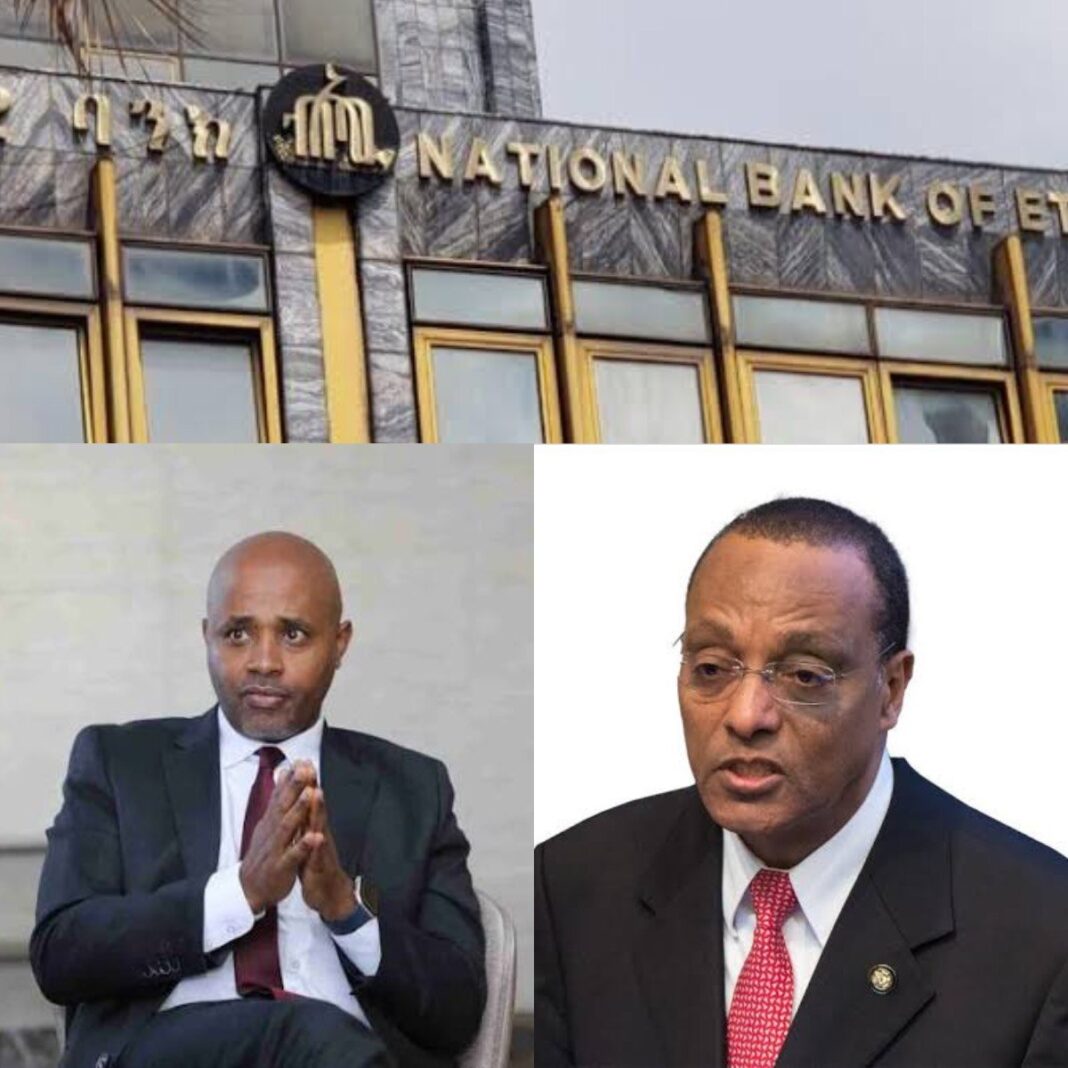
The National Bank of Ethiopia (NBE) has maintained its benchmark policy interest rate at 16 percent, keeping its monetary policy stance unchanged at the eighth meeting of its Monetary Policy Committee (MPC), held on November 3, 2026.
The Committee also retained the existing interest-rate corridor of ±300 basis points, reaffirming its commitment to a tight monetary stance as the central bank seeks to contain inflationary pressures and achieve its medium-term objective of single-digit inflation.
In its latest assessment, the MPC acknowledged that monetary and financial conditions have shown moderate loosening, while inflation forecasts continue to warrant a restrictive policy approach.
The decision comes amid accelerating monetary expansion. Broad money supply increased by 40.2 percent year-on-year, compared with 33.2 percent growth recorded in the same quarter of the previous fiscal year. The Committee noted that the expansion exceeded projected nominal GDP growth, although the recent acceleration was largely attributed to the accumulation of net foreign assets rather than the traditional domestic credit channel.
The development highlights the changing drivers of monetary expansion under the ongoing macroeconomic reform programme, which has brought substantial changes to the foreign exchange market and the central bank’s monetary policy framework.
The Committee also observed that Treasury bill yields and interbank money market rates have continued to decline, remaining negative in real terms since May 2026. However, commercial banks’ lending and deposit rates remained unchanged during the review quarter. The NBE attributed the short-term decline in market interest rates partly to excess reserves held by commercial banks, while other determining factors remained constant.
Despite the removal of the credit growth cap, the Committee noted that the banking industry had maintained strong resource mobilisation. During the first quarter of 2026/27, net deposits increased by 85.4 percent, while outstanding credit grew by 42.6 percent compared with the corresponding period of the previous fiscal year.
The fresh assessment also indicated that the banking sector remained sound, supported by adequate capital and low non-performing loans. However, the ratio of fresh loan disbursements to total resources mobilised by commercial banks remained broadly unchanged from the same period last year, despite substantial growth in deposits and the removal of the credit cap.
The NBE indicated that it would continue monitoring individual banks’ loan-to-deposit ratios and could introduce additional targeted reserve requirements if credit expansion threatens the inflation trajectory.
On the fiscal front, the Committee noted the government’s continued commitment to refraining from direct advances from the central bank. The government has maintained this position for more than 27 months, the longest period on record, a development the NBE said has contributed to price stability and supported its monetary policy objectives.
The external sector has also recorded substantial improvements compared with the pre-reform period, although the overall surplus declined during the review quarter. Export earnings, particularly from gold and coffee, continued to register positive growth, while imports also expanded considerably. Improved private transfers and capital account developments helped maintain an overall balance-of-payments surplus despite a wider trade deficit.
The monetary policy decision comes as the country continues implementing broader macroeconomic reforms aimed at strengthening foreign exchange market operations, improving monetary transmission and enhancing the country’s external position.
Further adjustments to foreign exchange retention arrangements, including the possibility of allowing exporters to retain up to 100 percent of their foreign currency earnings, have been among the issues surrounding the next phase of foreign exchange liberalisation. The phasing out of premiums and subsidies associated with the purchase of gold is also part of the broader reform agenda, alongside efforts to strengthen the formal foreign exchange market and improve export proceeds flowing through the banking system.
The international economic environment remains another concern for policymakers. Citing the IMF’s October 2026 World Economic Outlook, the NBE noted that global economic growth is projected at 3.1 percent in 2026 before recovering to 3.4 percent in 2027. Global headline inflation is forecast to reach 4.7 percent in 2026 before easing to 4.1 percent in 2027.
The Committee warned that prolonged geopolitical conflicts, elevated energy prices, renewed trade tensions and supply disruptions could further increase production and transportation costs, particularly for energy-importing economies. The duration of geopolitical tensions and the extent to which higher input costs translate into broader price increases remain important uncertainties for the inflation outlook.
To maintain its restrictive monetary stance, the MPC approved three principal measures. First, the NBE will retain the benchmark policy rate at 16 percent and maintain the existing ±300-basis-point interest-rate corridor. Second, it will continue using targeted additional reserve requirements based on individual banks’ loan-to-deposit ratios where necessary. Third, the central bank will absorb excess liquidity through open market operations, reinforcing the use of indirect monetary policy instruments.
The Committee said maintaining tight monetary conditions remains indispensable to achieving its medium-term single-digit inflation objective.
The MPC is scheduled to convene again at the end of January 2027, or earlier if economic conditions warrant further intervention.
The latest decision reinforces the central bank’s preference to maintain its restrictive monetary policy framework while relying increasingly on indirect instruments to manage liquidity and contain inflation.SECO