Young lender nearly doubles annual profit, expands customer base by 305,000 and strengthens its presence in Addis Ababa’s financial district
Ahadu Bank delivered a 77.6% increase in comparable earnings per share (EPS) in the 2025/26 financial year and proposed distributing 409 million birr to shareholders, marking a strong performance as the relatively young lender continues to expand its position in Ethiopia’s banking industry.
The bank’s audited financial statements for the year ended June 30, 2026, show that earnings per share reached 65 birr, compared with 183 birr in the previous financial year. However, the apparent decline reflects a change in the nominal value of ordinary shares from 500 birr to 100 birr. Adjusting for the fivefold change in share denomination, comparable EPS increased from approximately 36.6 birr to 65 birr, representing growth of 77.6%.
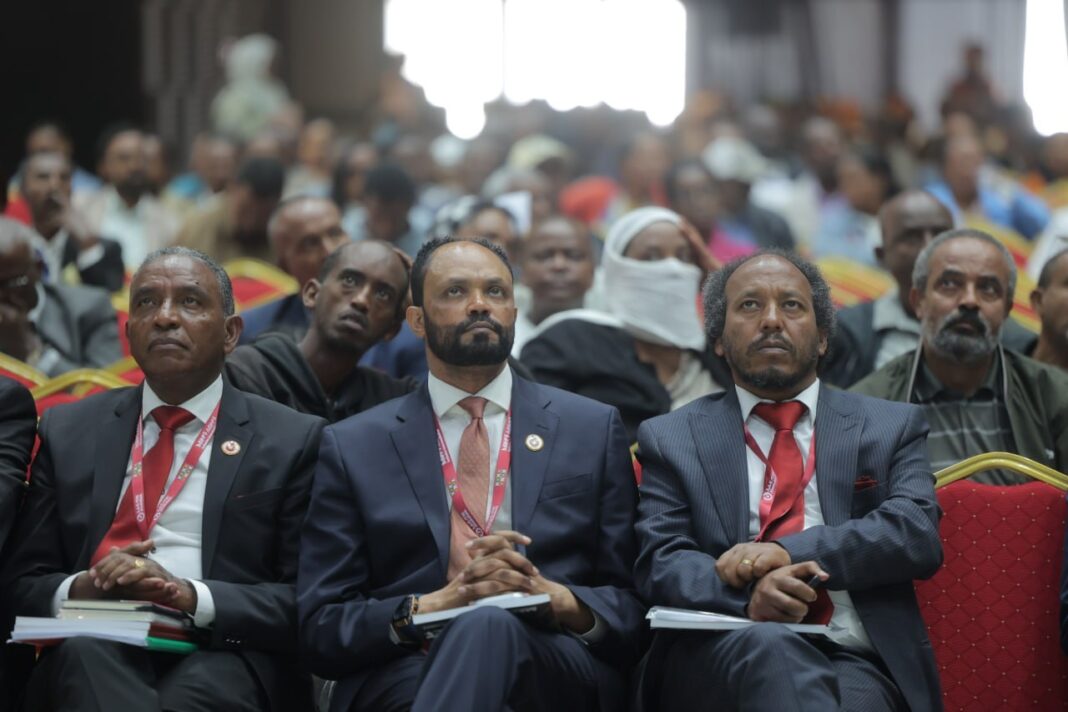
The impressive results were among the highlights presented at the bank’s fifth general meeting of shareholders held on Saturday, November 7. The atmosphere at the meeting reflected shareholders’ satisfaction with the financial performance and several promising developments registered during the year.
Ahadu Bank’s net profit after tax nearly doubled to 784.3 million birr, up from 399.4 million birr in 2024/25, representing a 96.4% increase. Profit before tax more than doubled to 1.07 billion birr from 502 million birr.
The Board of Directors recommended that 408.8 million birr of the bank’s appropriable net profit be distributed to shareholders as dividends or utilized to increase capital, subject to the payment modalities to be determined by the general meeting.
Total revenue increased to 3.2 billion birr from 2.2 billion birr in the preceding financial year, representing growth of approximately 47.7%. Total expenditure reached 2.1 billion birr, up 28.3%, leaving the bank with profit before tax of 1.07 billion birr.
Interest income accounted for 49.6% of total revenue, while non-interest income contributed the remaining 50.4%. Service charges and commission fees represented 89.3% of non-interest earnings, highlighting the growing importance of transaction-based income in the bank’s business model.
The bank’s total assets expanded by 42.5% to 14.3 billion birr, compared with 10 billion birr a year earlier. Customer deposits reached 10.5 billion birr, registering annual growth of 33%.
Its loan portfolio also expanded considerably. The bank disbursed net loans and advances amounting to 2.8 billion birr during the year, bringing its outstanding portfolio to 7.1 billion birr.
Import-related businesses received the largest share of credit at 21.2%, followed by export activities at 20%, domestic trade and services at 18.8%, and other sectors at 17.9%. Building and construction accounted for 13%, while industry received 5.7%.
The bank reported that 93.4% of its outstanding loans were classified as performing, while 4.5% were under special mention status. It said its non-performing loan ratio remained below industry standards.
International banking operations also generated USD 121.3 million in foreign currency earnings, an increase of USD 33 million, or 37.5%, from the previous year.
The performance was achieved despite challenges involving limited correspondent banking relationships, money transfer operators, prevailing credit limits and occasional liquidity constraints, according to the annual report.
Ahadu Bank’s customer acquisition drive was another major contributor to its expansion during the reporting year.
The bank added 305,372 deposit accounts, representing growth of 28%, bringing its total deposit accounts to 1.34 million by the end of June 2026.
Branches in Addis Ababa accounted for 186,339 of the newly opened accounts, while branches outside the capital contributed 119,033. Overall, 61% of the bank’s customer base was recruited through Addis Ababa branches, with the remaining 39% coming from other locations.
Digital banking expansion was another important component of the bank’s operational performance.
During the reporting year, Ahadu maintained its network of 21 ATMs and deployed 212 point-of-sale terminals. It also recruited 391 new banking agents, bringing the total to 415, while expanding merchant QR payment services to 1,897 locations.
The bank recruited 38,930 new ATM cardholders and 121,650 mobile and internet banking subscribers. By the end of June 2026, its customer base included 78,521 ATM cardholders and 220,467 mobile banking users.
It also launched the well accepted in house developed Ahadu Lekulu mobile banking application, offering account transfers, interbank and wallet transfers, school payments and other digital services.
In another initiative targeting small businesses, the bank introduced Mahider, a cash-flow-based lending platform developed in partnership with development partners. The digital solution uses real-time cash-flow analysis to provide tailored microloans to micro, small and medium-sized enterprises without conventional collateral requirements.
The bank’s expansion was also reflected in its workforce. Ahadu that leads by Mulugeta Beza recruited 115 additional employees during the year, bringing its total workforce to 1,901 by June 2026.
Beyond its financial and operational developments, Ahadu Bank, which joined the industry about five years ago, achieved another significant milestone in June when it took possession of a building in the heart of Addis Ababa’s financial district, strengthening its institutional presence in the capital.

Its paid-up capital reached 1.24 billion birr, while total equity increased by 56% to 2.34 billion birr.
The bank said it was awaiting Ethiopian Capital Market Authority approval of its prospectus to raise capital toward the 5-billion-birr minimum requirement set by the National Bank of Ethiopia. Currently its paid-up capital reached 1.24 billion birr.
Looking ahead; the bank identified digital financial services, financial inclusion, rural banking and support for MSMEs as strategic priorities. The leadership also disclosed that it plans to expand digital remittance services targeting the Ethiopian diaspora and strengthen its technological infrastructure.SECO