By Muluken Yewondwossen, Special to EBV
Governor Eyob Tekalign warns of decisive action against banks paying deposit interest upfront, as central bank says the practice distorts competition and undermines banking integrity
The National Bank of Ethiopia (NBE) has vowed to take decisive action against banks engaging in the upfront payment and compounding of deposit interest, with Governor Eyob Tekalign (PhD) describing the practice as completely illegal and warning that those responsible will face regulatory consequences.
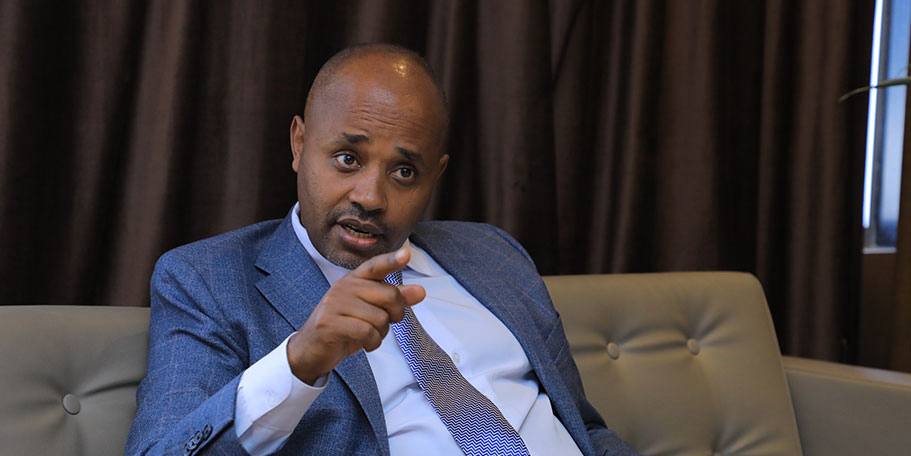
Speaking to the media on Tuesday, November 3, Eyob reaffirmed the central bank’s firm position against financial institutions that pay interest on time deposits before they mature and subsequently add those payments to the principal to generate further interest.
The governor said the central bank had already taken measures against bank leadership, including board members, in connection with the matter.
“It is a completely illegal act,” Eyob said, stressing that the NBE would not tolerate banks using such arrangements to attract deposits.
The warning follows a September 9, 2026 letter issued to all banks after the central bank identified cases in which financial institutions were recognizing and paying interest before depositors had maintained their funds for the agreed period.
The NBE specifically raised concerns about banks paying interest on the first day of a deposit contract and adding the amount to the principal. The additional interest then becomes part of the deposit balance and can itself generate further returns, even though the funds have not been maintained for the period required to earn those returns.
The central bank described the practice as malpractice, warning that it distorts the market, encourages unhealthy competition, creates opportunities for the misuse of public funds and threatens the sound operation of financial institutions.
It subsequently ordered banks to immediately stop calculating, recognizing and paying interest upfront, as well as compounding such payments with the principal before deposits reach maturity.
Financial industry sources previously told ETBusinessView that the practice had become a way for some banks to attract customers bringing substantial sums of money into time deposits, particularly amid intensifying competition for deposits.
The sources alleged that some established banks, including institutions that have faced public scrutiny over financial matters in recent months, were involved in arrangements of this nature.
They argued that paying interest before it is earned and allowing that amount to generate additional returns effectively creates financial value without a corresponding period of deposit maintenance.
Some industry insiders likened the practice to “printing money,” arguing that it gives selected depositors an artificial financial advantage while putting banks that comply with the rules at a competitive disadvantage. The characterization, however, reflects the assessment of industry sources rather than terminology used by the central bank.
The NBE’s September directive warned that it would take further supervisory and enforcement measures against institutions that failed to comply. Eyob’s latest remarks suggest that the regulator is now prepared to extend accountability beyond individual banking operations to the senior executives and board members overseeing them, according experts in the financial industry.
The central bank has also moved to address similar practices in the microfinance industry, issuing a separate warning to microfinance institutions in a letter dated September 23, 2026.
The crackdown comes as Ethiopia’s banking industry adjusts to a market-based interest-rate framework, under which financial institutions have greater flexibility in setting deposit rates, subject to regulatory requirements.
Experts underlined that with competition for deposits intensifying, the NBE’s position signals that banks will be expected to compete through legitimate pricing and financial products rather than advance interest arrangements that could undermine the integrity of deposit accounting and the wider banking system.SECO